5 Reasons a Reverse Mortgage May Not Be Right for You
Reverse mortgages can be a valuable financial tool for some homeowners, but they are not the right solution for everyone.


While a reverse mortgage can help eligible homeowners access home equity, eliminate an existing mortgage payment, or create additional retirement cash flow, there are important considerations to evaluate before moving forward.


The best financial decisions are informed ones. Understanding both the advantages and potential drawbacks of a reverse mortgage can help you determine whether it fits your long-term goals.


Here are five reasons why a reverse mortgage may not be the best choice for your situation.


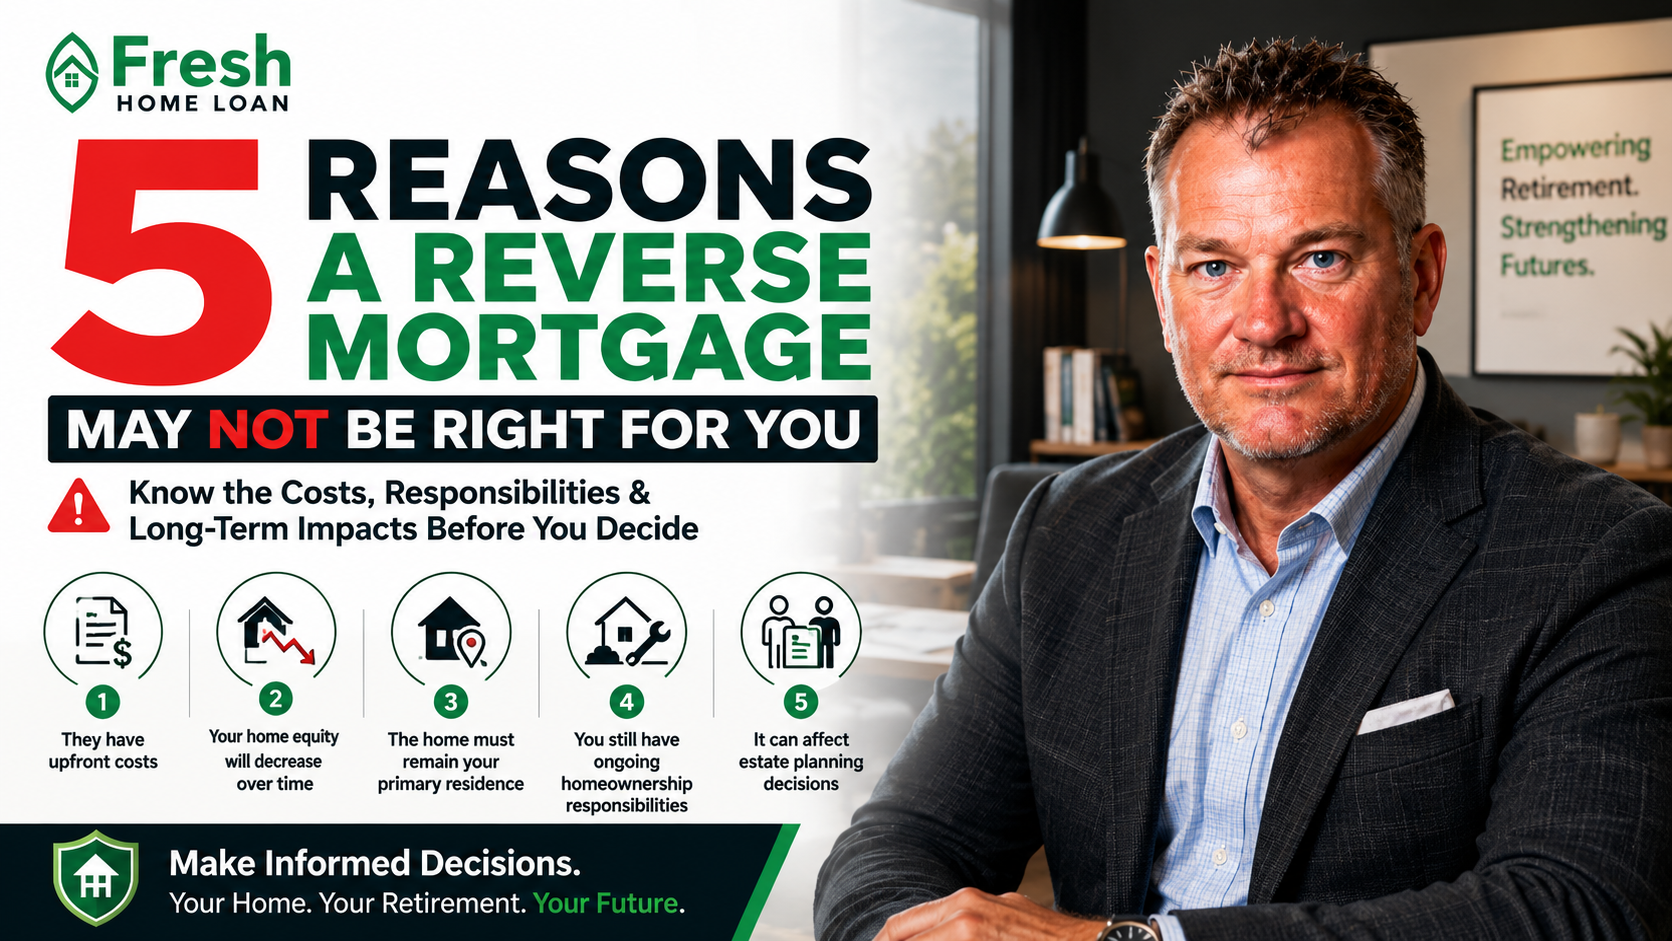
1. Reverse Mortgages Have Upfront Costs


Like traditional mortgages, reverse mortgages come with fees and closing costs.


Depending on the program, costs may include:


  • Origination fees
  • Appraisal fees
  • Title and escrow charges
  • Counseling fees
  • Mortgage insurance premiums (for FHA-insured HECM loans)


Many of these costs can be financed into the loan, which reduces the amount of equity available to you.


If you only plan to stay in the home for a short period of time, the benefits of a reverse mortgage may not outweigh the upfront expenses.


2. Your Home Equity Will Decrease Over Time


One of the primary features of a reverse mortgage is that no monthly mortgage payments are required on the loan balance.

However, interest and applicable fees continue to accrue over time.


As a result, the loan balance generally grows while the amount of remaining home equity decreases.


For homeowners who intend to leave the maximum amount of equity to heirs, this may be an important consideration.


That said, any remaining equity after the loan is repaid still belongs to the homeowner or their estate.


3. The Home Must Remain Your Primary Residence


Reverse mortgages are designed for homeowners who intend to continue living in the property.


If you move out permanently, sell the home, or relocate to a long-term care facility for an extended period, the loan may become due and payable.


For homeowners considering a move within the next few years, a reverse mortgage may not be the most practical solution.


Before moving forward, it's important to consider your future housing plans and whether you expect to remain in the home long term.


4. You Still Have Ongoing Homeownership Responsibilities


A common misconception is that a reverse mortgage eliminates all housing-related expenses.


While there are no required monthly mortgage payments, borrowers must continue to:


  • Pay property taxes
  • Maintain homeowners insurance
  • Keep the home in good condition
  • Pay HOA dues, if applicable


Failure to meet these obligations could place the loan in default.


A reverse mortgage works best when homeowners have a plan to comfortably manage these ongoing expenses.


5. It Can Affect Estate Planning Decisions


When the last borrower leaves the home, the reverse mortgage balance must be repaid.


In many cases, heirs choose to sell the property and use the proceeds to satisfy the loan. Others may refinance the balance into a traditional mortgage and keep the home.


While reverse mortgages are non-recourse loans—meaning heirs will never owe more than the home's value—families should still understand how the loan fits into their broader estate plan.


Having conversations with family members, financial advisors, and estate planning professionals ahead of time can help avoid confusion later.


What About Government Benefits?


One concern many homeowners have is whether a reverse mortgage will affect their retirement benefits.


Generally speaking:


  • Social Security retirement benefits are not affected.
  • Medicare benefits are not affected.
  • Supplemental Security Income (SSI) and Medicaid eligibility could be impacted if reverse mortgage proceeds are not managed properly.


Because every situation is different, homeowners should consult a qualified financial or tax professional before making a decision.


Final Thoughts


A reverse mortgage can be a powerful retirement planning tool, but it is not a one-size-fits-all solution.


For some homeowners, the benefits of accessing home equity and eliminating a monthly mortgage payment may outweigh the drawbacks. For others, alternative strategies may make more sense.


The key is understanding both the advantages and limitations before making a decision.


By reviewing your financial goals, future housing plans, and estate objectives, you can determine whether a reverse mortgage is the right fit for your retirement strategy.


Schedule a Consultation

Contact Fresh Home Loan today to discuss your options with an experienced mortgage professional.

https://freshhomeloan.com/schedule-a-meeting/


Garrick Werdmuller

President & CEO

Fresh Home Loan Inc.

510.282.5456 Call/Text

www.FreshHomeLoan.com


Follow us on social media:

https://www.facebook.com/freshhomeloan/

https://www.instagram.com/garrickwerdmuller/

https://www.linkedin.com/in/garrick-werdmuller-b044253/

https://www.youtube.com/@FreshHomeLoan

https://www.tiktok.com/@freshhomeloan


#ReverseMortgage #HECM #RetirementPlanning #HomeEquity #SeniorHomeowners #RetirementIncome #MortgageBroker #FinancialPlanning #Homeownership #FreshHomeLoan #RealEstate #FinancialFreedom


All loan approvals are conditional and not guaranteed and subject to lender review of all information. Loan is conditionally approved when the lender has issued approval in writing, but until all conditions are met, loan cannot be funded. Specified rates and products may not be available to all borrowers. Rates subject to change according to market conditions and agreed upon lock times set by the borrower. Fresh Home Loan Inc. is an Equal Opportunity Mortgage Broker in California. This licensee is performing acts for which a real estate license is required. Fresh Home Loan, Inc. is licensed by the California Department of Real Estate #02137513 NMLS # 2124104
By Garrick Werdmuller • October 28, 2026
My podcast is back! New Format. Real Estate Business Information and Motivation. Thanks for checking it out and subscribing! 😁 🎧 Our latest episode is the recording of our live UAD 3.6 webinar! Find out what's changing with real estate appraisals and what REALTORS® need to know. 👇 Listen on Spotify: https://open.spotify.com/episode/2qrzPT9wfur9Xs6o4J5mjB #NewPodcastEpisode #SpotifyPodcast #PodcastLife #MotivationAndInformation #RealConversations #RealEstatePodcast #MortgagePodcast #RealEstateMarketing #MortgageBroker #RealtorLife #BusinessMotivation #PersonalGrowth #LiveWebinar #UAD36 #FreshHomeLoan #BayAreaRealEstate #BakersfieldRealEstate
By Garrick Werdmuller • October 14, 2026
Win more listings by showing sellers the value of your local expertise
By Garrick Werdmuller • October 14, 2026
Reconnect, show your appreciation, and stay top of mind this holiday season
By Garrick Werdmuller • October 14, 2026
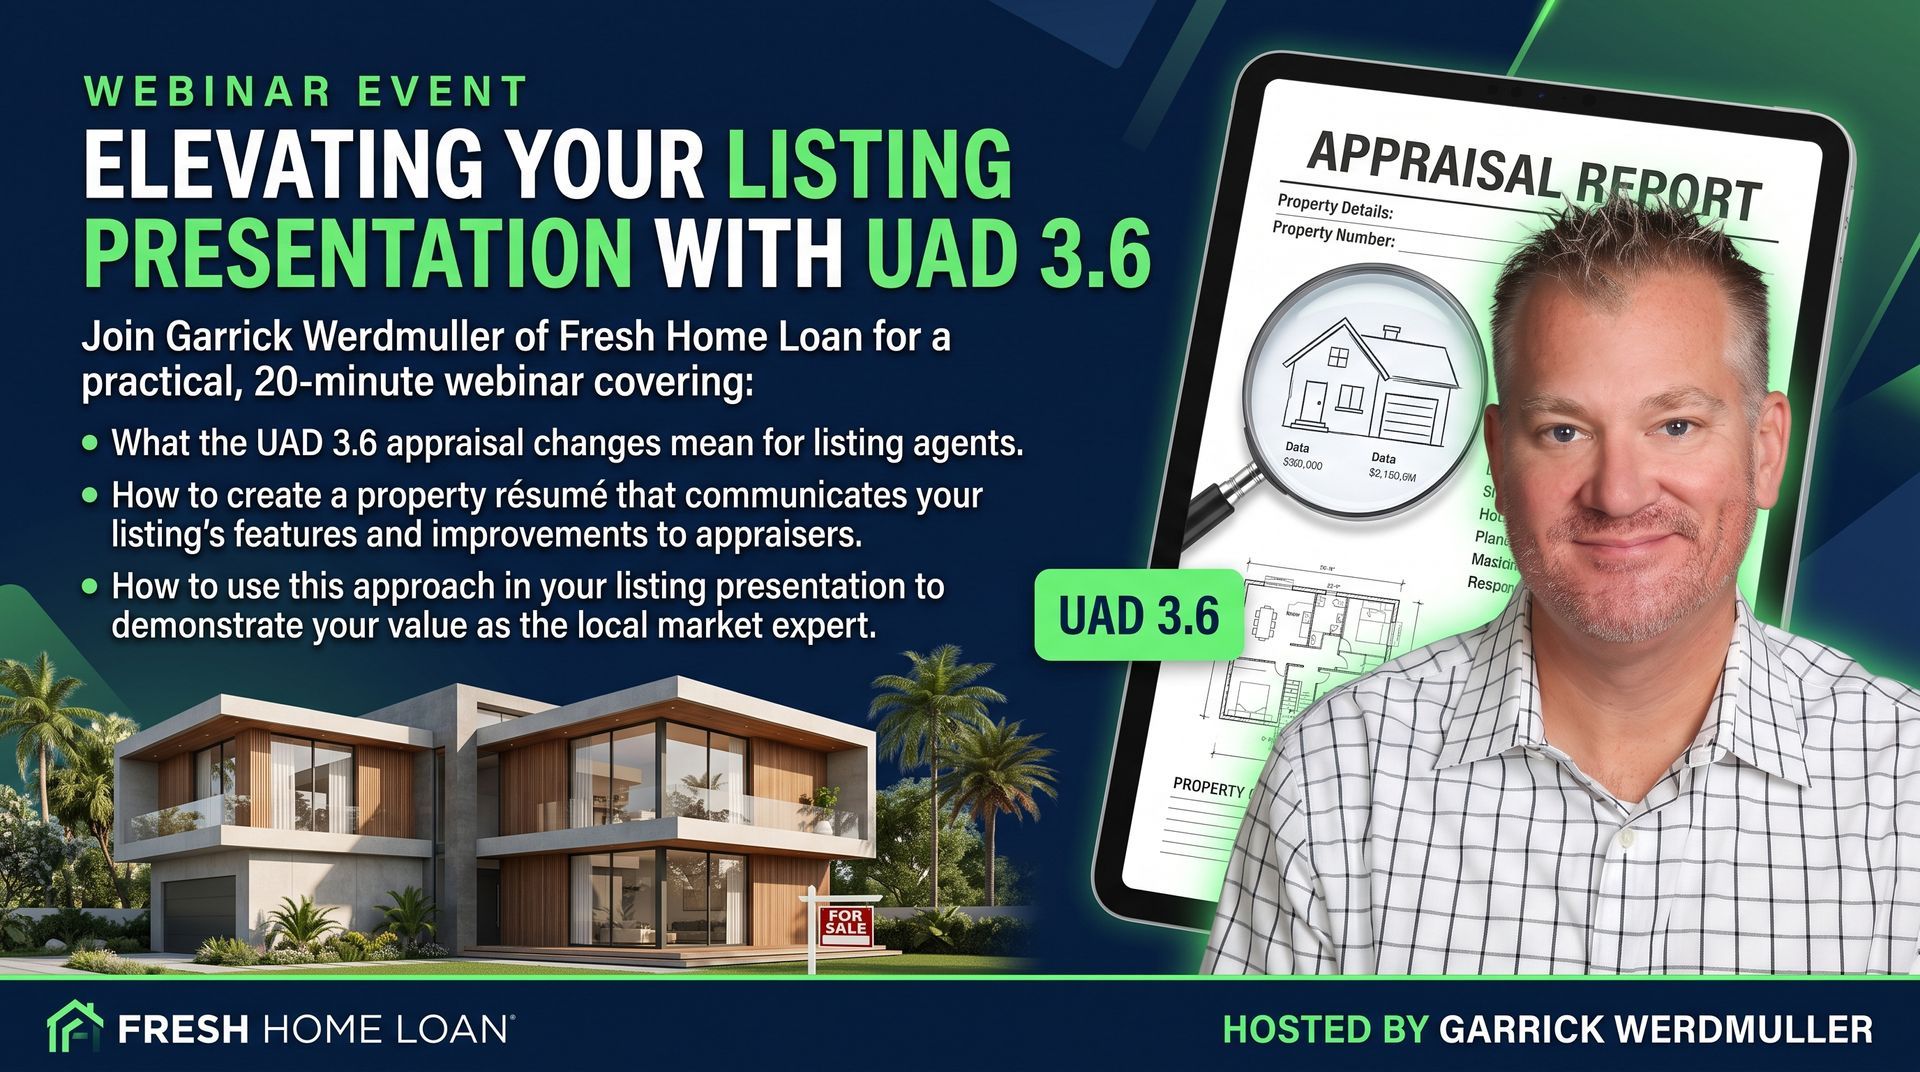
Friday, October 23, 2026 12:00–12:20 PM Pacific, followed by Q&A Register Here: https://us06web.zoom.us/meeting/register/vA1u-gAETAeKZj_nyHE9Ew In this episode of the GarrickWerdmullerSho , Garrick Werdmuller of Fresh Home Loan explains how real estate agents can use the UAD 3.6 appraisal transition to demonstrate their local expertise and give sellers a compelling reason to choose them. One idea you can put to work immediately: create a résumé for the property. Organize the home’s improvements, renovation dates, available permits, and unique features into a resource that supports your marketing and helps answer questions during the transaction. In this video, you’ll learn: What UAD 3.6 means and how appraisal reporting is changing Why specific improvement details are more useful than “updated throughout” What to include in a property résumé Questions to ask sellers before listing their home How to use AI to organize property information How to explain your preparation during a listing appointment What to ask your lender about the appraisal transition How Fresh Home Loan’s listing marketing tools can support your next listing Your local knowledge matters. Put technology to work helping you show sellers the value of that expertise. Friday, October 23, 2026 12:00–12:20 PM Pacific, followed by Q&A https://us06web.zoom.us/meeting/register/vA1u-gAETAeKZj_nyHE9Ew Connect with Garrick Werdmuller President & CEO | Fresh Home Loan Inc. 📱 Bay Area: (510) 282-5456 📱 Bakersfield: (661) 998-9588 📧 garrick@freshhomeloan.com 🌐 http s ://www.freshhomeloan.com Independent Mortgage Brokers that Work for the People. Presentation reflects information available in October 2026. Confirm current appraisal requirements and timelines with your lender. A property résumé is an optional preparation tool and does not guarantee an appraised value. #GarrickWerdmullerSho #UAD36 #ListingPresentation #RealEstateAgents #PropertyResume #FreshHomeLoan
By Garrick Werdmuller • October 5, 2026
Elevating Your Listing Presentation with UAD 3.6 Win more listings by showing sellers the value of your local expertise. Stay ahead of AI, technology, and industry changes—and turn what’s new into a competitive advantage at your next listing appointment. Instead of simply saying, “I know the neighborhood,” show them how you’ll document their property, explain the competition, and coordinate with the lender early. Join Us Live: Appraisals Are Changing: What You Need to Know About UAD 3.6 Friday, October 9, 2026 12:00–12:20 PM Pacific | Live on Zoom Register for the Webinar https://us06web.zoom.us/meeting/register/cGcRACrDSKifUbss1h88OQ#/registration Garrick Werdmuller | Fresh Home Loan  Independent Mortgage Brokers That Work for the People #UAD36 #ListingPresentation #WinMoreListings #RealtorEducation #LocalExpertise #AIForRealtors #RealEstateTechnology #RealEstateMarketing #FreshHomeLoan
By Garrick Werdmuller • October 1, 2026
Join me for a FREE live Zoom presentation about the new appraisal reporting standard and how to prepare for your next purchase, sale, or refinance.
By Garrick Werdmuller • September 30, 2026
New Title
By Garrick Werdmuller • September 17, 2026
Thinking about buying a home while mortgage rates are high? Learn how less competition, seller credits and negotiating power could save you money.
By Garrick Werdmuller • August 20, 2026
Looking to Consolidate Debt and do some Home Improvement? Got a “COVID Mortgage Rate”? Don’t Touch It!!!
By Garrick Werdmuller • August 11, 2026
Para muchos propietarios de 62 años o más , una hipoteca inversa puede ser mucho más que un préstamo: puede ser una poderosa herramienta de planificación financiera. Después de pasar décadas acumulando capital en una vivienda, muchos jubilados descubren que una parte importante de su patrimonio está concentrada en su propiedad. Una hipoteca inversa puede ayudar a aprovechar parte de ese capital y convertirlo en fondos disponibles, al mismo tiempo que permite a los propietarios continuar viviendo en la casa que aman. Aunque una hipoteca inversa no es adecuada para todos, puede ofrecer beneficios importantes para el prestatario adecuado. A continuación, presentamos cinco razones por las que vale la pena considerar una hipoteca inversa. 1. Generar Ingresos Adicionales Durante la Jubilación La jubilación suele implicar un cambio importante en el estilo de vida. Aunque los años de trabajo hayan quedado atrás, los gastos mensuales no desaparecen. Para muchos jubilados, una hipoteca inversa puede ayudar a cerrar la brecha entre los ingresos de jubilación y los gastos cotidianos. Los fondos recibidos de una hipoteca inversa pueden utilizarse para: Complementar los ingresos de jubilación Cubrir gastos del hogar Crear una red de seguridad financiera Mejorar el flujo de efectivo durante la jubilación Debido a que los fondos de una hipoteca inversa son dinero proveniente de un préstamo y no ingresos obtenidos por trabajo, generalmente no se consideran ingresos sujetos a impuestos. Para los propietarios que cuentan con un capital considerable en su vivienda, pero tienen activos líquidos limitados, una hipoteca inversa puede proporcionar una valiosa flexibilidad financiera. 2. Acceder al Capital de tu Vivienda de la Manera que Mejor se Adapte a Ti Una de las principales ventajas de una hipoteca inversa es la flexibilidad. Dependiendo del programa, los propietarios pueden elegir recibir los fondos como: Una suma global Pagos mensuales Una línea de crédito Una combinación de diferentes opciones de pago Esta flexibilidad permite adaptar el préstamo de acuerdo con los objetivos financieros y las necesidades de jubilación de cada propietario. Ya sea que necesites ingresos mensuales constantes o acceso ocasional a fondos, una hipoteca inversa puede estructurarse para adaptarse a tu situación. 3. Eliminar los Pagos de una Hipoteca Existente Muchos propietarios utilizan una hipoteca inversa para liquidar una hipoteca tradicional existente. Al eliminar un pago hipotecario mensual, los jubilados pueden mejorar significativamente su flujo de efectivo mensual. Para los propietarios que viven con ingresos fijos durante la jubilación, eliminar uno de sus gastos mensuales más importantes puede hacer que administrar el presupuesto sea mucho más sencillo. Aunque los prestatarios deben continuar pagando los impuestos sobre la propiedad, el seguro de vivienda y mantener la propiedad en buenas condiciones, eliminar un pago hipotecario mensual puede proporcionar un alivio financiero considerable. 4. Ayudar a Cubrir Gastos Inesperados La vida está llena de imprevistos, y algunos de los más costosos pueden estar relacionados con gastos médicos, reparaciones del hogar o emergencias familiares. Una hipoteca inversa puede proporcionar acceso a fondos cuando más se necesitan. Muchos propietarios utilizan los fondos de una hipoteca inversa para: Pagar gastos médicos Financiar modificaciones en la vivienda Cubrir costos de cuidados a largo plazo Realizar reparaciones importantes Crear un fondo para emergencias Tener acceso al capital acumulado en la vivienda puede ayudar a los jubilados a evitar depender de tarjetas de crédito con altas tasas de interés, préstamos personales o retirar fondos adicionales de sus cuentas de jubilación durante momentos difíciles. 5. Protección Incorporada Mediante un Préstamo Sin Recurso Una de las protecciones más importantes para los consumidores de las hipotecas inversas asegurad as por la FHA es que son préstamos sin recurso (non-recourse loans). Esto significa que ni el prestatario ni sus herederos deberán pagar más que el valor de la vivienda cuando el préstamo llegue a su vencimiento y sea exigible. Si eventualmente el saldo del préstamo supera el valor de la vivienda, el seguro hipotecario de la FHA cubre la diferencia. Esta protección puede brindar tranquilidad tanto a los propietarios como a sus familias, especialmente durante períodos de incertidumbre en el mercado inmobiliario. ¿Es una Hipoteca Inversa Adecuada para Ti? Una hipoteca inversa no se trata simplemente de pedir dinero prestado: se trata d e crear opciones. Para algunos propietarios, puede ayudar a mejorar el flujo de efectivo durante la jubilación, eliminar pagos hipotecarios mensuales, preservar cuentas de inversión y proporcionar una mayor seguridad financiera. La clave está en comprender cómo funciona el programa y evaluar si se alinea con tus objetivos a largo plazo. La situación de cada propietario es diferente. Por eso, hablar con un especialista experimentado en hipotecas inversas puede ayudarte a determinar si una hipoteca inversa es una buena opción para tu estrategia de jubilación. Reflexiones Finales Para los propietarios que cumplen con los requisitos, una hipoteca inversa puede ser una forma valiosa d e poner el capital acumulado en su vivienda a trabajar, sin tener que venderla ni asumir un pago hipotecario mensual obligatorio. Cuando se utiliza de manera estratégica, puede ayudar a crear flexibilidad, reducir el estrés financiero y proporcionar recursos adicionales durante la jubilación. Las mejores herramientas financieras son aquellas que respaldan tus objetivos y, para muchos jubilados, una hipoteca inversa puede ser una de ellas. Agenda una Consulta Contacta a Fresh Home Loan hoy mismo para analizar tus opciones con un profesional hipotecario con experiencia. https://freshhomeloan.com/schedule-a-meeting/ Garrick Werdmuller President & CEO Fresh Home Loan Inc. 510-282-5456 NMLS 242952 Diana Diaz Operations Manager 510-751-0303 customercare@freshomeloan.com Síguenos en redes sociales: https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@FreshHomeLoan https://www.tiktok.com/@freshhomeloan Todas las aprobaciones de préstamos están sujetas a revisión y aprobación final por parte del prestamista. Los préstamos se consideran aprobados únicamente cuando se emiten por escrito y se cumplen todas las condiciones. Las tasas y productos pueden no estar disponibles para todos los prestatarios y están sujetos a cambios según las condiciones del mercado y los términos de bloqueo de tasa. Fresh Home Loan Inc. es un Mortgage Broker de Igualdad de Oportunidades en California. Esta compañía realiza actos que requieren licencia de bienes raíces. Fresh Home Loan, Inc. está licenciada por el California Department of Real Estate #02137513 | NMLS #2124104. #HipotecaInversa #HECM #PlanificacionParaLaJubilacion #CapitalDeVivienda #PropietariosDeVivienda #IngresosDeJubilacion #AsesorHipotecario #PlanificacionFinanciera #PropiedadDeVivienda #FreshHomeLoan #BienesRaices #LibertadFinanciera