Reverse Mortgages in 2026: What Homeowners and Their Families Need to Know
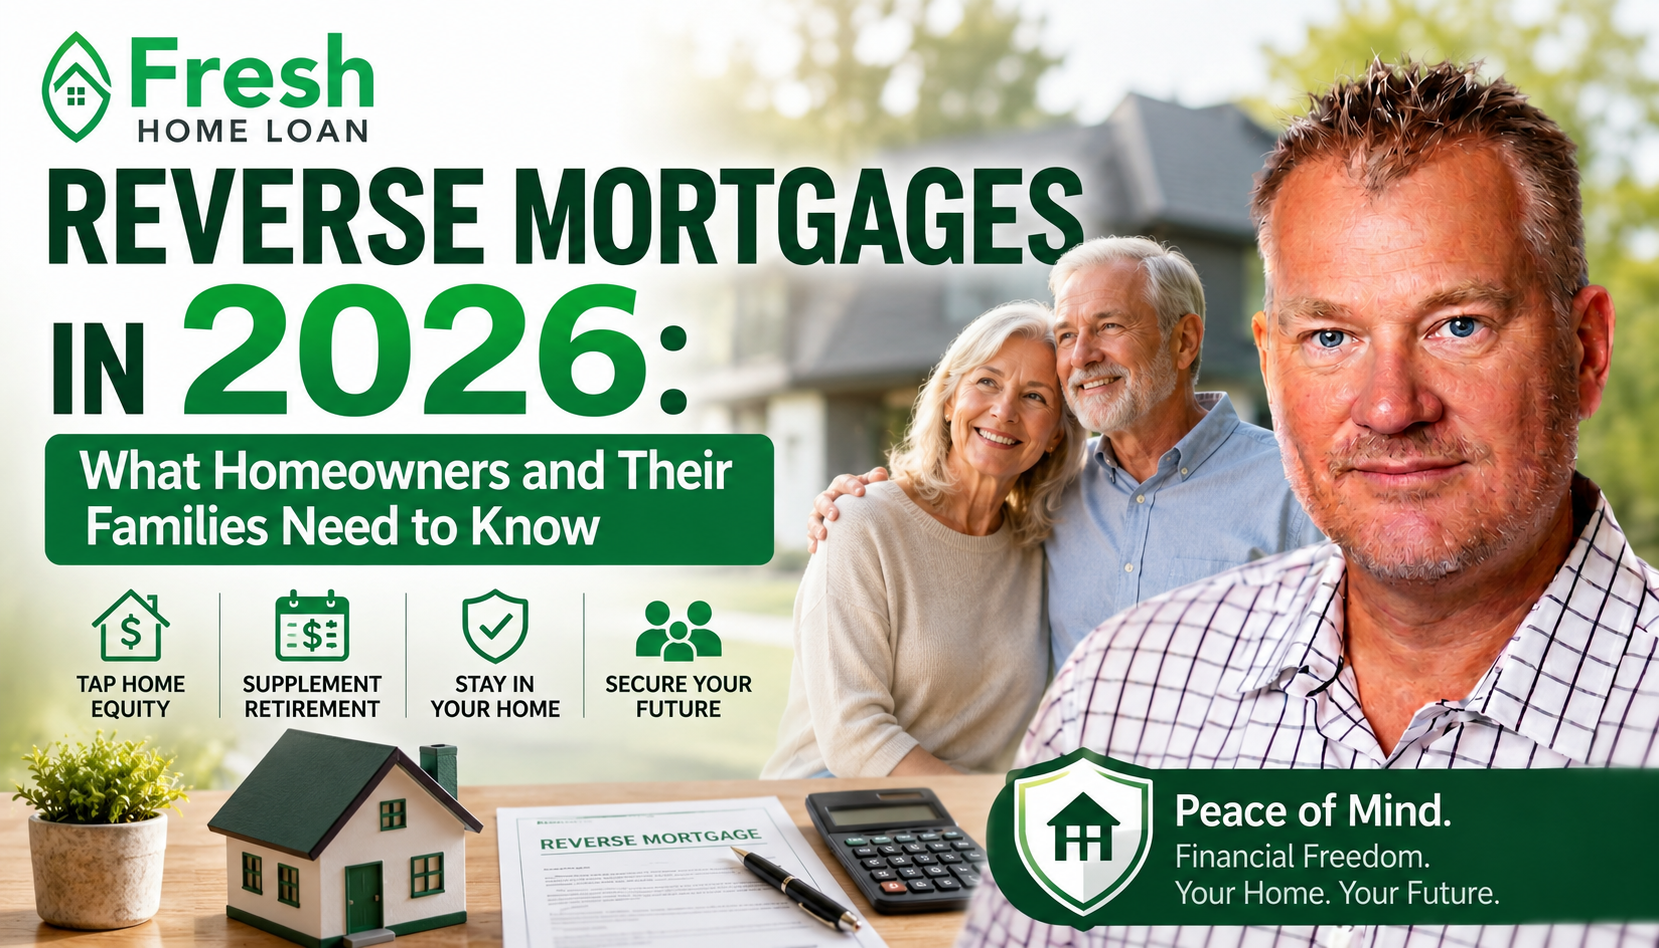
As retirement costs continue to rise and many homeowners sit on substantial home equity, reverse mortgages have become an increasingly important financial planning tool for seniors. While reverse mortgages aren't the right solution for everyone, they can provide flexibility, financial security, and peace of mind when used appropriately.


At Fresh Home Loan, we believe education comes first. Whether you're a homeowner exploring retirement options or an adult child helping aging parents evaluate their finances, understanding how reverse mortgages work is essential before making any decisions.


What Is a Reverse Mortgage?


A reverse mortgage allows eligible homeowners—typically age 62 or older—to convert a portion of their home's equity into cash without selling the property or taking on a traditional monthly mortgage payment.


Unlike a conventional mortgage where the borrower makes monthly payments to the lender, a reverse mortgage allows the homeowner to access their equity while continuing to live in the home. The loan balance grows over time and is generally repaid when the homeowner sells the property, permanently moves out, or passes away.


The most common reverse mortgage is the Home Equity Conversion Mortgage (HECM), which is insured by the Federal Housing Administration (FHA).


Why Reverse Mortgages Are Gaining Popularity


Today's retirees face different financial challenges than previous generations:


  • Rising healthcare costs
  • Longer life expectancy
  • Inflation impacting retirement income
  • Increased home values creating substantial equity
  • Desire to age in place rather than relocate


For many homeowners, a reverse mortgage provides access to wealth they've built over decades without requiring them to sell their home.


Common Ways Homeowners Use Reverse Mortgage Funds


Every homeowner's situation is different, but some of the most common uses include:


Supplementing Retirement Income

Many retirees use reverse mortgage proceeds to help cover everyday living expenses, allowing retirement savings and investment accounts to last longer.


Paying Off an Existing Mortgage

One of the most popular strategies is eliminating an existing mortgage payment. Removing that monthly obligation can significantly improve cash flow during retirement.


Covering Medical Expenses

Healthcare costs can quickly become one of the largest retirement expenses. Reverse mortgage proceeds may help cover medical bills, in-home care, or other healthcare-related costs.


Home Improvements and Accessibility Upgrades

Many seniors use funds to modify their homes with accessibility features such as ramps, walk-in showers, wider doorways, or other improvements that support aging in place.


Creating a Financial Safety Net

A reverse mortgage line of credit can serve as an emergency reserve, giving homeowners access to funds when unexpected expenses arise.


Why Work with a Mortgage Broker for a Reverse Mortgage?


Many consumers are surprised to learn that reverse mortgages are available through mortgage brokers—not just companies that exclusively offer reverse mortgage products.


Working with an independent mortgage broker offers several advantages:


Access to Multiple Lenders

A broker can compare programs from multiple lenders rather than offering only one company's products. This can help homeowners find a solution that best fits their goals.


Personalized Guidance

Reverse mortgages involve important financial decisions. A knowledgeable mortgage broker can explain available options, answer questions, and help evaluate whether a reverse mortgage makes sense for your situation.


Competitive Pricing

Because brokers have access to multiple lending sources, they can often help borrowers compare rates, fees, and product features.


Ongoing Support

A broker serves as an advocate throughout the process, helping coordinate documentation, counseling requirements, and lender communication.


Where Can You Get a Reverse Mortgage?

Homeowners generally have several options when seeking a reverse mortgage:


Traditional Banks and Credit Unions

Some financial institutions offer reverse mortgage products through their lending divisions.


Specialized Reverse Mortgage Companies

These lenders focus primarily on reverse mortgage products and often have dedicated teams experienced in senior lending solutions.


Independent Mortgage Brokers

Mortgage brokers can provide access to multiple lenders and programs while helping borrowers compare options.


Online Mortgage Providers

Many lenders now offer digital application processes that allow homeowners to complete much of the transaction remotely.


Benefits of Reverse Mortgages

When used appropriately, reverse mortgages can provide significant advantages.


No Required Monthly Mortgage Payment

Borrowers are generally not required to make monthly principal and interest payments as long as they continue to meet loan obligations.


Stay in Your Home

Many homeowners choose a reverse mortgage because it allows them to remain in a home they love while accessing accumulated equity.


Flexible Payment Options

Funds may be received as:

  • A lump sum
  • Monthly payments
  • A line of credit
  • A combination of these options


Tax-Free Proceeds

Reverse mortgage proceeds are generally considered loan proceeds rather than taxable income. Homeowners should consult with a qualified tax advisor regarding their specific situation.


Non-Recourse Protection

HECM reverse mortgages are non-recourse loans, meaning borrowers or their heirs generally will not owe more than the home's value when the loan becomes due.


Potential Drawbacks to Consider

A reverse mortgage can be a valuable tool, but it is important to understand the potential downsides.


Loan Costs

Reverse mortgages include fees, interest charges, and, in some cases, mortgage insurance premiums.


Reduced Home Equity

As funds are borrowed and interest accrues, the remaining equity in the property decreases over time.


Ongoing Property Obligations

Borrowers must continue to:


  • Pay property taxes
  • Maintain homeowners insurance
  • Keep the property in good condition
  • Occupy the home as their primary residence


Failure to meet these obligations may result in default.


Estate Planning Considerations

A reverse mortgage can impact inheritance plans. Family members should understand how the loan will be handled when the borrower passes away or permanently leaves the home.


Long-Term Care Situations

If a borrower moves into assisted living or another facility for an extended period, the loan may become due and payable.


Questions to Ask Before Getting a Reverse Mortgage


Before moving forward, consider these important questions:


  • How long do I plan to stay in my home?
  • What are my retirement income needs?
  • Have I explored other financial options?
  • How will this decision affect my heirs?
  • Am I comfortable maintaining the responsibilities of homeownership?
  • Have I discussed the decision with trusted family members and financial professionals?


The Importance of Reverse Mortgage Counseling


For FHA-insured HECM loans, independent counseling is required before obtaining the loan.


This counseling helps ensure homeowners understand:


  • How reverse mortgages work
  • Available alternatives
  • Loan costs and obligations
  • Potential impacts on their financial future


The goal is to help borrowers make informed decisions based on their individual circumstances.


The Bottom Line


A reverse mortgage is neither inherently good nor bad—it is simply a financial tool. For some homeowners, it can provide retirement security, increased cash flow, and the ability to remain in their homes for years to come. For others, alternative solutions may be more appropriate.


The key is understanding all available options and working with experienced professionals who put education first.

At Fresh Home Loan, we believe homeowners deserve objective guidance, clear explanations, and personalized solutions. If you're exploring reverse mortgages for yourself or helping a family member evaluate retirement options, our team is here to answer your questions and help you make an informed decision.


Schedule a Consultation

Want to learn whether a reverse mortgage may be right for your situation?


Contact Fresh Home Loan today to discuss your options with an experienced mortgage professional.

https://freshhomeloan.com/schedule-a-meeting/


Garrick Werdmuller

President & CEO

Fresh Home Loan Inc.

510.282.5456 Call/Text

NMLS #242952

www.FreshHomeLoan.com


You may also enjoy: 


  • Jumbo Reverse Mortgages in the Bay Area: Unlocking Home Equity for Retirement

https://www.freshhomeloan.com/jumbo-reverse-mortgages-in-the-bay-area-unlocking-home-equity-for-retirement

  • One Broker, More Options: Traditional and Reverse Mortgages Under One Roof

https://www.freshhomeloan.com/one-broker-more-options-traditional-and-reverse-mortgages-under-one-roof

  • What Happens When You Sell a Home With a Reverse Mortgage

https://www.freshhomeloan.com/what-happens-when-you-sell-a-home-with-a-reverse-mortgage


Follow us on social media:

https://www.facebook.com/freshhomeloan/

https://www.instagram.com/garrickwerdmuller/

https://www.linkedin.com/in/garrick-werdmuller-b044253/

https://www.youtube.com/@FreshHomeLoan

https://www.tiktok.com/@freshhomeloan


#ReverseMortgage #HECM #RetirementPlanning #HomeEquity #SeniorHomeowners #RetirementIncome #MortgageBroker #FinancialPlanning #Homeownership #FreshHomeLoan #RealEstate #FinancialFreedom


All loan approvals are conditional and not guaranteed and subject to lender review of all information. Loan is conditionally approved when the lender has issued approval in writing, but until all conditions are met, loan cannot be funded. Specified rates and products may not be available to all borrowers. Rates subject to change according to market conditions and agreed upon lock times set by the borrower. Fresh Home Loan Inc. is an Equal Opportunity Mortgage Broker in California. This licensee is performing acts for which a real estate license is required. Fresh Home Loan, Inc. is licensed by the California Department of Real Estate #02137513 NMLS # 2124104
By Garrick Werdmuller August 20, 2026
Looking to Consolidate Debt and do some Home Improvement? Got a “COVID Mortgage Rate”? Don’t Touch It!!!
By Garrick Werdmuller August 11, 2026
Para muchos propietarios de 62 años o más , una hipoteca inversa puede ser mucho más que un préstamo: puede ser una poderosa herramienta de planificación financiera. Después de pasar décadas acumulando capital en una vivienda, muchos jubilados descubren que una parte importante de su patrimonio está concentrada en su propiedad. Una hipoteca inversa puede ayudar a aprovechar parte de ese capital y convertirlo en fondos disponibles, al mismo tiempo que permite a los propietarios continuar viviendo en la casa que aman. Aunque una hipoteca inversa no es adecuada para todos, puede ofrecer beneficios importantes para el prestatario adecuado. A continuación, presentamos cinco razones por las que vale la pena considerar una hipoteca inversa. 1. Generar Ingresos Adicionales Durante la Jubilación La jubilación suele implicar un cambio importante en el estilo de vida. Aunque los años de trabajo hayan quedado atrás, los gastos mensuales no desaparecen. Para muchos jubilados, una hipoteca inversa puede ayudar a cerrar la brecha entre los ingresos de jubilación y los gastos cotidianos. Los fondos recibidos de una hipoteca inversa pueden utilizarse para: Complementar los ingresos de jubilación Cubrir gastos del hogar Crear una red de seguridad financiera Mejorar el flujo de efectivo durante la jubilación Debido a que los fondos de una hipoteca inversa son dinero proveniente de un préstamo y no ingresos obtenidos por trabajo, generalmente no se consideran ingresos sujetos a impuestos. Para los propietarios que cuentan con un capital considerable en su vivienda, pero tienen activos líquidos limitados, una hipoteca inversa puede proporcionar una valiosa flexibilidad financiera. 2. Acceder al Capital de tu Vivienda de la Manera que Mejor se Adapte a Ti Una de las principales ventajas de una hipoteca inversa es la flexibilidad. Dependiendo del programa, los propietarios pueden elegir recibir los fondos como: Una suma global Pagos mensuales Una línea de crédito Una combinación de diferentes opciones de pago Esta flexibilidad permite adaptar el préstamo de acuerdo con los objetivos financieros y las necesidades de jubilación de cada propietario. Ya sea que necesites ingresos mensuales constantes o acceso ocasional a fondos, una hipoteca inversa puede estructurarse para adaptarse a tu situación. 3. Eliminar los Pagos de una Hipoteca Existente Muchos propietarios utilizan una hipoteca inversa para liquidar una hipoteca tradicional existente. Al eliminar un pago hipotecario mensual, los jubilados pueden mejorar significativamente su flujo de efectivo mensual. Para los propietarios que viven con ingresos fijos durante la jubilación, eliminar uno de sus gastos mensuales más importantes puede hacer que administrar el presupuesto sea mucho más sencillo. Aunque los prestatarios deben continuar pagando los impuestos sobre la propiedad, el seguro de vivienda y mantener la propiedad en buenas condiciones, eliminar un pago hipotecario mensual puede proporcionar un alivio financiero considerable. 4. Ayudar a Cubrir Gastos Inesperados La vida está llena de imprevistos, y algunos de los más costosos pueden estar relacionados con gastos médicos, reparaciones del hogar o emergencias familiares. Una hipoteca inversa puede proporcionar acceso a fondos cuando más se necesitan. Muchos propietarios utilizan los fondos de una hipoteca inversa para: Pagar gastos médicos Financiar modificaciones en la vivienda Cubrir costos de cuidados a largo plazo Realizar reparaciones importantes Crear un fondo para emergencias Tener acceso al capital acumulado en la vivienda puede ayudar a los jubilados a evitar depender de tarjetas de crédito con altas tasas de interés, préstamos personales o retirar fondos adicionales de sus cuentas de jubilación durante momentos difíciles. 5. Protección Incorporada Mediante un Préstamo Sin Recurso Una de las protecciones más importantes para los consumidores de las hipotecas inversas asegurad as por la FHA es que son préstamos sin recurso (non-recourse loans). Esto significa que ni el prestatario ni sus herederos deberán pagar más que el valor de la vivienda cuando el préstamo llegue a su vencimiento y sea exigible. Si eventualmente el saldo del préstamo supera el valor de la vivienda, el seguro hipotecario de la FHA cubre la diferencia. Esta protección puede brindar tranquilidad tanto a los propietarios como a sus familias, especialmente durante períodos de incertidumbre en el mercado inmobiliario. ¿Es una Hipoteca Inversa Adecuada para Ti? Una hipoteca inversa no se trata simplemente de pedir dinero prestado: se trata d e crear opciones. Para algunos propietarios, puede ayudar a mejorar el flujo de efectivo durante la jubilación, eliminar pagos hipotecarios mensuales, preservar cuentas de inversión y proporcionar una mayor seguridad financiera. La clave está en comprender cómo funciona el programa y evaluar si se alinea con tus objetivos a largo plazo. La situación de cada propietario es diferente. Por eso, hablar con un especialista experimentado en hipotecas inversas puede ayudarte a determinar si una hipoteca inversa es una buena opción para tu estrategia de jubilación. Reflexiones Finales Para los propietarios que cumplen con los requisitos, una hipoteca inversa puede ser una forma valiosa d e poner el capital acumulado en su vivienda a trabajar, sin tener que venderla ni asumir un pago hipotecario mensual obligatorio. Cuando se utiliza de manera estratégica, puede ayudar a crear flexibilidad, reducir el estrés financiero y proporcionar recursos adicionales durante la jubilación. Las mejores herramientas financieras son aquellas que respaldan tus objetivos y, para muchos jubilados, una hipoteca inversa puede ser una de ellas. Agenda una Consulta Contacta a Fresh Home Loan hoy mismo para analizar tus opciones con un profesional hipotecario con experiencia. https://freshhomeloan.com/schedule-a-meeting/ Garrick Werdmuller President & CEO Fresh Home Loan Inc. 510-282-5456 NMLS 242952 Diana Diaz Operations Manager 510-751-0303 customercare@freshomeloan.com Síguenos en redes sociales: https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@FreshHomeLoan https://www.tiktok.com/@freshhomeloan Todas las aprobaciones de préstamos están sujetas a revisión y aprobación final por parte del prestamista. Los préstamos se consideran aprobados únicamente cuando se emiten por escrito y se cumplen todas las condiciones. Las tasas y productos pueden no estar disponibles para todos los prestatarios y están sujetos a cambios según las condiciones del mercado y los términos de bloqueo de tasa. Fresh Home Loan Inc. es un Mortgage Broker de Igualdad de Oportunidades en California. Esta compañía realiza actos que requieren licencia de bienes raíces. Fresh Home Loan, Inc. está licenciada por el California Department of Real Estate #02137513 | NMLS #2124104. #HipotecaInversa #HECM #PlanificacionParaLaJubilacion #CapitalDeVivienda #PropietariosDeVivienda #IngresosDeJubilacion #AsesorHipotecario #PlanificacionFinanciera #PropiedadDeVivienda #FreshHomeLoan #BienesRaices #LibertadFinanciera 
By Garrick Werdmuller August 11, 2026
Las hipotecas inversas pueden ser una herramienta financiera valiosa para algunos propietarios, pero no son la solución adecuada para todos. Aunque una hipoteca inversa puede ayudar a propietarios elegibles a acceder al capital acumulado en su vivienda, eliminar un pago hipotecario existente o generar flujo de efectivo adicional durante la jubilación, es importante evaluar ciertos factores antes de tomar una decisión. Las mejores decisiones financieras son aquellas que se toman con información. Comprender tanto las ventajas como las posibles desventajas de una hipoteca inversa puede ayudarte a determinar si se adapta a tus objetivos a largo plazo. A continuación, presentamos cinco razones por las que una hipoteca inversa puede no ser la mejor opción para tu situación. 1. Las Hipotecas Inversas Tienen Costos Iniciales Al igual que las hipotecas tradicionales, las hipotecas inversas incluyen tarifas y costos de cierre. Dependiendo del programa, los costos pueden incluir: Tarifas de originación Tarifas de tasación Gastos de título y escrow Tarifas de asesoramiento Primas de seguro hipotecario (para préstamos HECM asegurados por la FHA) Muchos de estos costos pueden financiarse como parte del préstamo, lo que reduce la cantidad de capital disponible para ti. Si solo planeas permanecer en la vivienda durante un período corto de tiempo, los beneficios de una hipoteca inversa podrían no compensar los gastos iniciales. 2. El Capital Acumulado en tu Vivienda Disminuirá con el Tiempo Una de las principales características de una hipoteca inversa es que no se requieren pagos hipotecarios mensuales sobre el saldo del préstamo. Sin embargo, los intereses y las tarifas correspondientes continúan acumulándose con el tiempo. Como resultado, el saldo del préstamo generalmente aumenta mientras que la cantidad de capital restante en la vivienda disminuye. Para los propietarios que desean dejar la mayor cantidad posible de capital a sus herederos, esto puede ser un factor importante a considerar. Dicho esto, cualquier capital que quede después de pagar el préstamo sigue perteneciendo al propietario o a su patrimonio. 3. La Vivienda Debe Seguir Siendo tu Residencia Principal Las hipotecas inversas están diseñadas para propietarios que planean continuar viviendo en la propiedad. Si te mudas permanentemente, vendes la vivienda o te trasladas a una residencia de cuidados a largo plazo durante un período prolongado, el préstamo podría vencer y ser exigible. Para los propietarios que están considerando mudarse dentro de los próximos años, una hipoteca inversa podría no ser la solución más práctica. Antes de seguir adelante, es importante considerar tus planes de vivienda a futuro y si esperas permanecer en la propiedad a largo plazo. 4. Aún Tendrás Responsabilidades como Propietario Un error común es pensar que una hipoteca inversa elimina todos los gastos relacionados con la vivienda. Aunque no se requieren pagos hipotecarios mensuales, los prestatarios deben continuar: Pagando los impuestos sobre la propiedad Manteniendo un seguro de vivienda vigente Conservando la vivienda en buenas condiciones Pagando las cuotas de HOA, si corresponde No cumplir con estas obligaciones podría ocasionar que el préstamo entre en incumplimiento. Una hipoteca inversa funciona mejor cuando los propietarios cuentan con un plan para manejar cómodamente estos gastos continuos. 5. Puede Afectar las Decisiones de Planificación Patrimonial Cuando el último prestatario deja la vivienda, el saldo de la hipoteca inversa debe ser pagado. En muchos casos, los herederos optan por vender la propiedad y utilizar los ingresos para pagar el préstamo. Otros pueden refinanciar el saldo mediante una hipoteca tradicional y conservar la vivienda. Aunque las hipotecas inversas son préstamos sin recurso (non-recourse), l o que significa que los herederos nunca deberán pagar más que el valor de la vivienda, las familias deben comprender cómo encaja el préstamo dentro de su plan patrimonial general. Tener conversaciones con familiares, asesores financieros y profesionales de planificación patrimonial con anticipación puede ayudar a evitar confusiones en el futuro. ¿Qué Pasa con los Beneficios del Gobierno? Una preocupación común entre muchos propietarios es si una hipoteca inversa afectará sus beneficios de jubilación. En términos generales: Los beneficios de jubilación del Seguro Social no se ven afectados. Los beneficios de Medicare no se ven afectados. La elegibilidad para Supplemental Security Income (SSI) y Medicaid podría verse afectada si los fondos provenientes de una hipoteca inversa no se administran correctamente. Debido a que cada situación es diferente, los propietarios deben consultar con un profesional financiero o fiscal calificado antes de tomar una decisión. Reflexiones Finales Una hipoteca inversa puede ser una herramienta poderosa para la planificación de la jubilación, pero no es una solución universal. Para algunos propietarios, los beneficios de acceder al capital acumulado en su vivienda y eliminar un pago hipotecario mensual pueden superar las desventajas. Para otros, estrategias alternativas podrían tener más sentido. La clave está en comprender tanto las ventajas como las limitaciones antes de tomar una decisión. Al revisar tus objetivos financieros, tus planes de vivienda a futuro y tus objetivos patrimoniales, puedes determinar si una hipoteca inversa es la opción adecuada para tu estrategia de jubilación. Agenda una Consulta Contacta a Fresh Home Loan hoy mismo para analizar tus opciones con un profesional hipotecario con experiencia. https://freshhomeloan.com/schedule-a-meeting/ Garrick Werdmuller President & CEO Fresh Home Loan Inc. 510-282-5456 NMLS 242952 Diana Diaz Operations Manager 510-751-0303 customercare@freshomeloan.com Síguenos en redes sociales: https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@FreshHomeLoan https://www.tiktok.com/@freshhomeloan Todas las aprobaciones de préstamos están sujetas a revisión y aprobación final por parte del prestamista. Los préstamos se consideran aprobados únicamente cuando se emiten por escrito y se cumplen todas las condiciones. Las tasas y productos pueden no estar disponibles para todos los prestatarios y están sujetos a cambios según las condiciones del mercado y los términos de bloqueo de tasa. Fresh Home Loan Inc. es un Mortgage Broker de Igualdad de Oportunidades en California. Esta compañía realiza actos que requieren licencia de bienes raíces. Fresh Home Loan, Inc. está licenciada por el California Department of Real Estate #02137513 | NMLS #2124104. #HipotecaInversa #HECM #PlanificacionParaLaJubilacion #CapitalDeVivienda #PropietariosDeVivienda #IngresosDeJubilacion #AsesorHipotecario #PlanificacionFinanciera #PropiedadDeVivienda #FreshHomeLoan #BienesRaices #LibertadFinanciera
By Garrick Werdmuller August 11, 2026
Aunque tanto un HELOC como un HELOAN permiten a los propietarios acceder al capital acumulado en su propiedad sin tener que refinanciar su primera hipoteca existente, están diseñados para diferentes necesidades financieras. ¿Qué es un HELOC? Una Home Equity Line of Credit (HELOC), o línea de crédito sobre el valor acumulado de la vivienda, es una línea de crédito renovable respaldada por el capital de su propiedad. Puede considerarse similar a una tarjeta de crédito, pero generalmente con una tasa de interés mucho más baja porque está respaldada por su vivienda. En lugar de recibir todos los fondos de una sola vez, usted obtiene la aprobación para un límite máximo de crédito y puede retirar dinero según lo necesite durante el período de disposición. Esta flexibilidad hace que un HELOC sea particularmente atractivo para propietarios que tienen gastos continuos o cuyos costos aún no están completamente definidos. Por ejemplo, si está remodelando una cocina, construyendo una ADU (Accessory Dwelling Unit), pagando la matrícula universitaria durante varios semestres o simplemente quiere tener acceso a fondos para futuras oportunidades, un HELOC le permite pedir prestado únicamente lo que necesita y cuando lo necesita. En muchos casos, los propietarios pagan intereses solamente sobre la cantidad que realmente han utilizado, y no sobre el total de la línea de crédito aprobada. Un HELOC también puede funcionar como una red de seguridad financiera. Muchos propietarios establecen un HELOC y mantienen los fondos disponibles para emergencias, oportunidades de inversión o gastos inesperados. Debido a que el dinero está disponible cuando se necesita, ofrece una flexibilidad que un préstamo tradicional de suma global no puede proporcionar. ¿Qué es un HELOAN? Un Home Equity Loan (HELOAN), o préstamo sobre el valor acumulado de la vivienda, es una segunda hipoteca tradicional que proporciona una cantidad fija de dinero en un solo desembolso inicial. A diferencia de un HELOC, donde los fondos pueden utilizarse a lo largo del tiempo, un HELOAN entrega el monto total del préstamo al momento del cierre y se paga mediante mensualidades fijas durante un plazo determinado. Muchos propietarios prefieren un HELOAN cuando saben exactamente cuánto dinero necesitan y quieren la tranquilidad de contar con un pago fijo y predecible. Si está financiando un proyecto importante de mejora de su vivienda con un presupuesto definido, pagando deudas con tasas de interés elevadas, comprando una propiedad de inversión o cubriendo un gasto grande de una sola vez, un HELOAN puede ofrecer certeza y estructura. Debido a que el monto del préstamo, el pago mensual y el calendario de pagos quedan establecidos desde el cierre, muchos prestatarios valoran la simplicidad de saber exactamente cuánto deberán pagar cada mes. No es necesario administrar diferentes retiros de fondos ni preocuparse por saldos fluctuantes. Para los propietarios que prefieren una solución de financiamiento sencilla y estructurada, un HELOAN puede ser una excelente opción. ¿Cuál Opción es Mejor? La respuesta depende de sus objetivos. Si necesita flexibilidad , quiere tener acceso continuo a fondos o espera que sus gastos ocurran a lo largo del tiempo, un HELOC puede ser la opción que mejor se adapte a sus necesidades. Si sabe exactamente cuánto dinero necesita y prefiere un pago fijo con un calendario de liquidación definido , un HELOAN puede ser una opción más conveniente. La buena noticia es que ambos productos pueden permitir a los propietarios acceder al capital acumulado en su vivienda sin modificar su primera hipoteca existente. Para los propietarios que aseguraron tasas hipotecarias históricamente bajas, esto puede representar una ventaja significativa frente a refinanciar el saldo total de su hipoteca a las tasas actuales del mercado. ¿Te gustaría saber qué opción es adecuada para ti? Para programar una cita con Garrick Werdmuller, Presidente y CEO de Fresh Home Loan Inc. , visite: https://freshhomeloan.com/schedule-a-meeting/ Garrick Werdmuller President & CEO Fresh Home Loan Inc. 510-282-5456 NMLS 242952 Diana Diaz Operations Manager 510-751-0303 customercare@freshomeloan.com Redes Sociales https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@FreshHomeLoan https://www.tiktok.com/@freshhomeloan Todas las aprobaciones de préstamos están sujetas a revisión y aprobación final por parte del prestamista. Los préstamos se consideran aprobados únicamente cuando se emiten por escrito y se cumplen todas las condiciones. Las tasas y productos pueden no estar disponibles para todos los prestatarios y están sujetos a cambios según las condiciones del mercado y los términos de bloqueo de tasa. Fresh Home Loan Inc. es un Mortgage Broker de Igualdad de Oportunidades en California. Esta compañía realiza actos que requieren licencia de bienes raíces. Fresh Home Loan, Inc. está licenciada por el California Department of Real Estate #02137513 | NMLS #2124104. #HELOC #HELOAN #PropietariosDeVivienda #ConsejosParaPropietarios #Hipotecas #FinanzasPersonales #FinanciamientoDeVivienda #AgenteInmobiliario #FreshHomeLoan #BienesRaices #ConstruccionDePatrimonio #AsesoriaHipotecaria #LibertadFinanciera
By Garrick Werdmuller August 3, 2026
BAKERSFIELD, Calif. — Fresh Home Loan Inc., an Independent California mortgage brokerage, is proud to announce its expansion into Bakersfield, bringing homebuyers, homeowners, real estate professionals, and investors greater access to competitive financing solutions and personalized mortgage guidance. Unlike traditional banks that offer only their own loan products, Fresh Home Loan works with a network of wholesale lenders to help clients find financing that best fits their unique financial goals and circumstances. "We're excited to bring our independent mortgage brokerage model to Bakersfield," said Garrick Werdmuller, President and Broker of Record at Fresh Home Loan. "Every client has a different story, and having access to multiple lending partners allows us to explore more financing solutions than a single lender can typically provide." Fresh Home Loan offers a wide range of mortgage programs, including: Conventional, FHA, VA, and Jumbo financing First-time homebuyer programs Low down payment and zero down payment options for qualified borrowers Bank statement loans for self-employed borrowers DSCR investor loans ITIN financing Private money and bridge financing HELOCs and home equity solutions Construction and renovation financing Reverse mortgages The Bakersfield expansion also strengthens Fresh Home Loan's commitment to supporting the local real estate community. The company plans to host educational workshops, networking events, and marketing collaborations designed to help real estate professionals grow their businesses while providing valuable education to consumers throughout Kern County. Fresh Home Loan's mission is simple: provide honest advice, competitive loan options, fast communication, and exceptional customer service from application to closing. "Our goal isn't simply to close loans," Werdmuller added. "We want to become a trusted mortgage resource for families, Realtors, builders, and investors throughout Bakersfield and Central California." For more information about Fresh Home Loan or to schedule a complimentary mortgage consultation, visit FreshHomeLoan.com or contact the Bakersfield office. About Fresh Home Loan Inc. Fresh Home Loan Inc. is an independent California mortgage brokerage dedicated to helping clients achieve homeownership through education, personalized service, and access to a broad network of wholesale lending partners. Serving communities throughout California, Fresh Home Loan offers financing solutions for first-time buyers, move-up buyers, investors, and homeowners seeking to refinance or leverage their home equity. Garrick Werdmuller President CEO Fresh Home Loan Inc 510.282.5456 call/text NMLS 242952 www.FreshHomeLoan.com Socials: https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@freshhomeloan-garrickwerdm316 All loan approvals are conditional and not guaranteed and subject to lender review of all information. Loan is conditionally approved when lender has issued approval in writing, but until all conditions are met, loan cannot be funded. Specified rates and [products may not be available to all borrowers. Rates subject to change according to market conditions and agreed upon lock times set by borrower. Fresh Home Loan Inc. is an Equal Opportunity Mortgage Broker in California. This licensee is performing acts for which a real estate license is required. Fresh Home Loan, Inc. is licensed by the California Department of Real Estate #02137513 NMLS # 2124104
By Garrick Werdmuller August 3, 2026
"Wait... I didn't know that. Maybe I qualify." "Here's something most homebuyers don't know." "Every mortgage has a set of guidelines, whether it is conventional to Jumbo, FHA, VA, USDA, ITIN, Revers Mortgage, whatever – there is an investor that purchases that loan according to a set of guidelines.” "But many lenders and especially the big banks add something called 'overlays.' " "An overlay is simply an extra rule the bank creates to reduce its own risk." For example, maybe the loan program allows a 620 credit score—but that bank won't go below 680. Or maybe the program allows a higher debt-to-income ratio say 43% but the bank only goes to 38% —but the bank has a stricter limit." "As an independent mortgage broker, I work with multiple wholesale lenders." "If one lender has stricter overlays, another lender may follow the standard program guidelines more closely or offer a different program that fits your situation." "That doesn't mean every loan can be approved—but it does mean one 'no' isn't always the final answer." According to the CFPB: Consumer Financial Protection Bureau these are the 3 most common reasons a loan is denied and how we can help: 1. Income This is the #1 reason. Examples: Self-employed with large tax write-offs. Commission or bonus income that's difficult to document. Retirees living on assets. Real estate investors. 1099 contractors. Recently changed jobs. Many banks have more conservative debt to income ratio overlays, leaving the borrower qualify for less. They also may not have niche loans for self-employed borrowers who sometimes have trouble qualifying off tax returns. Often times, real estate investors have deductions on that make it difficult to cash flow on their returns. Independent mortgage brokers like Fresh Home Loan Inc. can often access lenders that accept: Bank statement loans Asset utilization/depletion DSCR loans for investors Alternative income documentation 2. Credit Every lender has different overlays. Examples: Credit score just below the bank's minimum. Limited credit history. Recent bankruptcy or foreclosure. A manual underwriting situation. One lender may decline the loan while another approves it under a different program. 3. The Property or Collateral The borrower may qualify, but the property doesn't. Examples: Non-warrantable condos Deferred maintenance Unique property Many times, large banks simply won't finance these situations, while Independent Mortgage brokers can. Unlike traditional banks that offer only their own loan products, Fresh Home Loan works with a network of wholesale lenders to help clients find financing that best fits their unique financial goals and circumstances. For more information: https://www.freshhomeloan.com/contact-us Call or text: 510.282.5456 Email: Garick@freshhomeloan.com Garrick Werdmuller President CEO Fresh Home Loan Inc 510.282.5456 call/text NMLS 242952 www.FreshHomeLoan.com Socials: https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@freshhomeloan-garrickwerdm316 All loan approvals are conditional and not guaranteed and subject to lender review of all information. Loan is conditionally approved when lender has issued approval in writing, but until all conditions are met, loan cannot be funded. Specified rates and [products may not be available to all borrowers. Rates subject to change according to market conditions and agreed upon lock times set by borrower. Fresh Home Loan Inc. is an Equal Opportunity Mortgage Broker in California. This licensee is performing acts for which a real estate license is required. Fresh Home Loan, Inc. is licensed by the California Department of Real Estate #02137513 NMLS # 2124104 #HomeLoans #MortgageTips #HomeBuying #FirstTimeHomeBuyer #Realtor #RealtorLife #MortgageBroker #Chase #WellsFargo
By Garrick Werdmuller July 22, 2026
Thanks for visiting this page! I wanted to invite you to check out the system we're now using for our Open House marketing. I think it's a great opportunity for us to collaborate and help generate more leads together. It has a TON of features, including: 🏡 Property Websites Mobile-friendly listing websites Recently Sold property pages Lead capture tools Easy sharing on social media and email 🖨️ Print Marketing Open House Flyers Promotional Flyers Infographics Open House Sign-In Sheets Property Reports Jumbo Postcards Sign Riders 📢 Active Listing Marketing Coming Soon Flyers Just Listed Flyers Under Contract Flyers In Escrow Flyers Just Sold Flyers Go Green Flyers Property Reports and Marketing Pieces 📋 Listing Presentations Pre-Listing Presentations Neighborhood Reports Beautiful Infographics designed to help win listings 🏠 Buyer Resources Neighborhood Reports Buyer Infographics Market information to educate your clients 📬 Lead Generation Tools Sign Riders with lead capture Multiple postcard sizes and marketing campaigns Print and digital marketing working together Garrick Werdmuller President & CEO Fresh Home Loan, Inc. 🌐 https://freshhomeloan.com #ListingsToLeads #RealEstateMarketing #RealtorTools #ListingPresentation #OpenHouse #RealEstateLeads #MortgageBroker #FreshHomeLoan #RealtorSuccess #DigitalMarketing #RealEstateTechnology #LeadGeneration #RealEstateTraining #MarketingForRealtors
By Garrick Werdmuller July 9, 2026
I was recently referred to a woman in need of financing assistance by a realtor buddy. She had a lot of problems with delinquent taxes, deferred maintenance on her properties, overdue bills, it was a bad situation. She had two properties: her primary residence and an investment property. They were both free and clear, so she had equity, the problem was she had no income and the houses were in such bad shape no one would lend on them. I actually had great confidence I could find a home for her investment property, but I was actually denied 18 times! However, #19 said, and I quote ”Garrick, I am not mad at this loan” and off we went! Within three weeks we were closed and funded. The borrower actually lost her phone and the realtor and I were worried and he drove to one house and I drove to the other and we found her! Got her signed and now she has cash to pay the taxes and bills, rehab the property, and get a new phone! Who do you know that will do as much as I will do for you? Questions? https://www.freshhomeloan.com/contact-us Socials: https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@FreshHomeLoan https://www.tiktok.com/@freshhomeloan All loan approvals are conditional and not guaranteed and subject to lender review of all information. Loan is conditionally approved when the lender has issued approval in writing, but until all conditions are met, loan cannot be funded. Specified rates and products may not be available to all borrowers. Rates subject to change according to market conditions and agreed upon lock times set by the borrower. Fresh Home Loan Inc. is an Equal Opportunity Mortgage Broker in California. This licensee is performing acts for which a real estate license is required. Fresh Home Loan, Inc. is licensed by the California Department of Real Estate #02137513 NMLS # 2124104 #HardMoney #RealEstate #HardMoneyLender #RealEstateInvesting #FixAndFlip #HardMoneyLoans #FreshHomeLoan #BayArea
By Garrick Werdmuller July 7, 2026
Shopping for a HELOC or HELOAN? Learn the five most important factors to compare, including costs, appraisal requirements, loan options, and closing times before choosing a lender. 1. Do They Offer Multiple HELOC and HELOAN Programs? Not every lender has the same products. Some only offer one HELOC. Others don't offer fixed-rate HELOANs at all. Some have higher loan limits, lower minimum draws, or allow investment properties while others don't. At Fresh Home Loan, we shop multiple lenders to find the program that fits your goals—not force your goals into one lender's program. 2. What Will the Appraisal Cost You? One of the biggest surprises for homeowners is appraisal fees. Some lenders require a full appraisal that can cost hundreds of dollars and delay the process. Others may qualify for an Automated Valuation Model (AVM) or desktop valuation, saving both time and money. We'll tell you upfront what your property is likely to need before you spend a dime. 3. How Fast Can They Close? If you're consolidating debt, paying for a remodel, buying out a partner, or financing an ADU, timing matters. Many lenders take 30-60 days. We regularly close HELOCs and HELOANs much faster because we know the process and work with lenders that prioritize speed. The sooner your loan closes, the sooner you can put your equity to work. 4. What Are the Total Costs? Don't focus only on the interest rate. Compare: Closing costs Lender fees Annual fees Early payoff penalties (if any) Minimum draw requirements Fixed vs. variable rate options The lowest advertised rate isn't always the least expensive loan. We'll walk through every cost before you decide. 5. Can You Actually Reach Your Loan Officer? A HELOC isn't a one-size-fits-all loan. Questions come up about: Borrowing limits Draw periods Fixed-rate options Using funds for ADUs Debt consolidation Investment properties Working with someone who answers the phone and explains your options can save you thousands of dollars—and a lot of frustration. At Fresh Home Loan, you'll work directly with experienced mortgage professionals who guide you from application to funding. Ready to Put Your Home Equity to Work? Whether you're planning a remodel, consolidating debt, building an ADU, paying for college, or simply want access to your home's equity, we'll help you compare the best HELOC and HELOAN options available. Why homeowners choose Fresh Home Loan: Multiple HELOC and HELOAN programs Fast closings Low fees Honest advice with no pressure Experienced local mortgage professionals Apply today or contact Fresh Home Loan for a free, no-obligation review of your home's equity options. For more information give Garrick Werdmuller a call at 510.282.5456 or visit: https://freshhomeloan.com/schedule-a-meeting/ Garrick Werdmuller President CEO Fresh Home Loan Inc 510.282.5456 call/text NMLS 242952 www.FreshHomeLoan.com You may also enjoy: HELOC vs. HELOAN: Unlocking Your Home's Equity Without Touching Your First Mortgage https://www.freshhomeloan.com/heloc-vs-heloan-unlocking-your-home-s-equity-without-touching-your-first-mortgage HELOC vs Credit Card: Which Is Better for Homeowners? https://www.freshhomeloan.com/heloc-vs-credit-card-which-is-better-for-homeowners Understanding the Difference Between a HELOC and a HELOAN https://www.freshhomeloan.com/understanding-the-difference-between-a-heloc-and-a-heloan How Does a HELOC work? https://www.freshhomeloan.com/how-does-a-heloc-work Socials: https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@FreshHomeLoan https://www.tiktok.com/@freshhomeloan #HELOC #HELOAN #HomeEquity #HomeEquityLoan #HomeEquityLineOfCredit #CashOutRefinance #MortgageTips #HomeownerTips #HomeImprovement #ADU #DebtConsolidation #MortgageBroker #MortgageAdvice #RealEstate #Homeowners #FinancialFreedom #FreshHomeLoan #CaliforniaMortgage #BayAreaRealEstate #BakersfieldRealEstate All loan approvals are conditional and not guaranteed and subject to lender review of all information. Loan is conditionally approved when the lender has issued approval in writing, but until all conditions are met, loan cannot be funded. Specified rates and products may not be available to all borrowers. Rates subject to change according to market conditions and agreed upon lock times set by the borrower. Fresh Home Loan Inc. is an Equal Opportunity Mortgage Broker in California. This licensee is performing acts for which a real estate license is required. Fresh Home Loan, Inc. is licensed by the California Department of Real Estate #02137513 NMLS # 2124104
By Garrick Werdmuller June 30, 2026
For years, the 30-year fixed mortgage has been the "default" choice for homebuyers. But if you're purchasing a higher-priced home that requires a jumbo loan, there may be a smarter option worth considering: the 7/6 Jumbo Adjustable-Rate Mortgage (ARM). With today's interest rates, many jumbo borrowers are discovering that a 7/6 ARM can provide a significantly lower initial interest rate than a traditional 30-year fixed mortgage, helping reduce monthly payments while increasing purchasing power. What Is a 7/6 Jumbo ARM? A 7/6 Jumbo ARM is a mortgage designed for loan amounts that exceed conforming loan limits. Here's how it works: Your interest rate is fixed for the first seven years. After those seven years, the rate adjusts every six months based on a published market index plus a predetermined margin. The loan includes adjustment caps that limit how much the rate can change over time. For many borrowers, seven years provides plenty of time before any adjustment could occur. Why Consider a Jumbo ARM? Lower Interest Rate One of the biggest advantages is that 7/6 Jumbo ARMs typically offer lower starting interest rates than comparable 30-year fixed mortgages. That lower rate may translate into: Lower monthly mortgage payments Greater purchasing power Reduced interest costs during the fixed-rate period For buyers shopping in competitive markets, this can make a meaningful difference. Who Is a Good Candidate? A 7/6 Jumbo ARM may be an excellent fit if you: Expect to move within seven years May refinance before the fixed period ends Receive bonuses or increasing income over time Prefer lower monthly payments today Are purchasing a luxury or high-value Why a 7/6 Jumbo ARM Could Be a Better Choice Than a 30-Year Fixed When most people think about getting a mortgage, they automatically assume a 30-year fixed loan is the only option. But if you're financing a higher-priced home with a jumbo loan , you may have another option that could save you money. A 7/6 Jumbo Adjustable-Rate Mortgage (ARM) often comes with a lower interest rate than a traditional 30-year fixed mortgage. That lower rate can translate into a lower monthly payment, reduced interest costs during the fixed period, and even greater buying power. How Does a 7/6 Jumbo ARM Work? A 7/6 Jumbo ARM keeps your interest rate fixed for the first seven years of the loan. During that time, your payment remains stable, just like a fixed-rate mortgage. After the initial seven-year period, the interest rate adjusts every six months according to the terms of the loan and current market conditions. These loans also include adjustment caps that limit how much the rate can change. Why Are Buyers Choosing a 7/6 Jumbo ARM? Many homebuyers don't keep the same mortgage for 30 years. Life changes, families grow, careers evolve, and homeowners often refinance or move before seven years have passed. For buyers who expect they may: Move to another home Refinance if rates improve Upgrade or downsize Build additional equity ...a 7/6 Jumbo ARM may offer significant savings during the years they actually expect to own the loan. Benefits of a 7/6 Jumbo ARM Lower starting interest rate than many 30-year fixed jumbo loans Lower monthly payments Increased purchasing power Stable payment for the first seven years An excellent option for borrowers with a shorter mortgage timeline Is It Right for Everyone? Not necessarily. A 30-year fixed mortgage still provides the certainty of the same interest rate for the life of the loan, making it a great option for borrowers planning to stay in their home for many years. The best mortgage depends on your financial goals, how long you expect to own the home, and your long-term plans. Let's Compare Your Options Don't assume the 30-year fixed mortgage is automatically the best choice. At Fresh Home Loan , we compare multiple loan programs—including fixed-rate mortgages and Jumbo ARMs—to help you choose the option that best fits your goals. If you're shopping for a luxury home or need jumbo financing, let's run the numbers together. You may be surprised how much a 7/6 Jumbo ARM could save you. Ready to Explore Your Jumbo Loan Options? Every homebuyer's situation is different. Whether you're purchasing your dream home or refinancing an existing jumbo mortgage, I'll help you compare a traditional 30-year fixed with a 7/6 Jumbo ARM so you can make an informed decision based on your goals—not assumptions. Let's run the numbers together and see which option works best for you. https://freshhomeloan.com/schedule-a-meeting/ Garrick Werdmuller President & CEO Fresh Home Loan Inc. 510.282.5456 Call/Text www.FreshHomeLoan.com Follow us on social media: https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@FreshHomeLoan https://www.tiktok.com/@freshhomeloan #JumboLoan #JumboMortgage #JumboARM #MortgageBroker #FreshHomeLoan #LuxuryHomes #LuxuryRealEstate #CaliforniaRealEstate #HomeLoans #MortgageRates #HomeBuying #DreamHome #MortgageTips #FirstTimeHomeBuyer #Refinance #AdjustableRateMortgage #RealEstate #BayAreaRealEstate #BakersfieldRealEstate #IndependentMortgageBroker All loan approvals are conditional and not guaranteed and subject to lender review of all information. Loan is conditionally approved when the lender has issued approval in writing, but until all conditions are met, loan cannot be funded. Specified rates and products may not be available to all borrowers. Rates subject to change according to market conditions and agreed upon lock times set by the borrower. Fresh Home Loan Inc. is an Equal Opportunity Mortgage Broker in California. This licensee is performing acts for which a real estate license is required. Fresh Home Loan, Inc. is licensed by the California Department of Real Estate #02137513 NMLS # 2124104