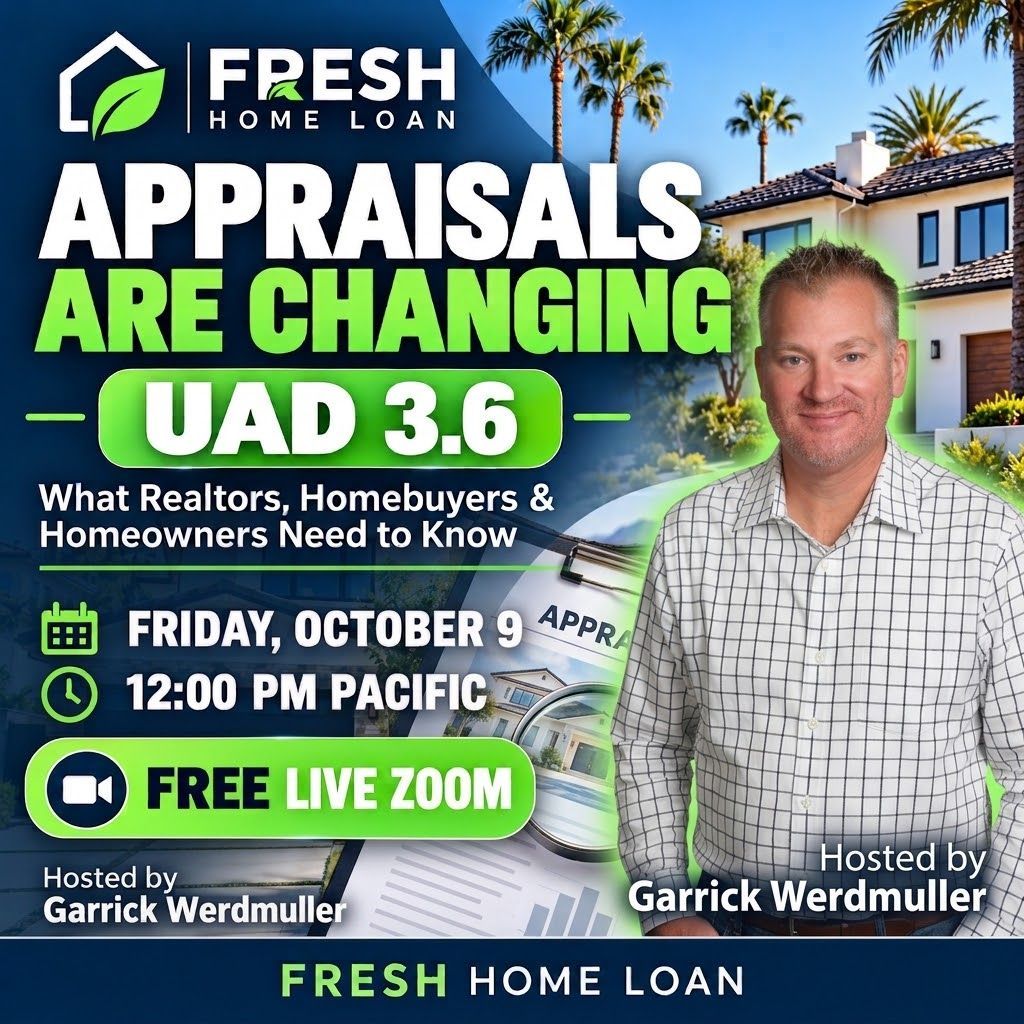
Appraisals Are Changing: What Realtors, Homebuyers, and Homeowners Need to Know

New Title
A major update is changing how appraisers document homes—and understanding it can help you prepare for your next real estate transaction.

Fannie Mae and Freddie Mac are introducing Uniform Appraisal Dataset 3.6, commonly called UAD 3.6. This update replaces familiar appraisal forms with a flexible report that adjusts to the property and the type of appraisal assignment. Its purpose is to make property information more consistent and easier to review.


Whether you’re helping clients, purchasing a home, or preparing to sell or refinance, here’s what you should know.


1. Appraisal Reports Will Look Different

For years, appraisers have used different forms for houses, condominiums, manufactured homes, and other properties. The redesigned Uniform Residential Appraisal Report organizes those assignments within a dynamic reporting structure.

The report’s sections reflect the property being evaluated. During the transition, you may encounter different formats depending on the lender and assignment.


2. More Details About the Home Will Be Documented

The updated reporting includes more specific property information, such as separate interior and exterior condition and quality ratings. The Pennsylvania Association of Realtors also highlights more detailed reporting of kitchen and bathroom updates, green features, construction type, and converted spaces.

For homeowners and listing agents, this makes preparation valuable. A description such as “remodeled kitchen” is more useful when you can explain when the work was completed and what was changed.


My recommendation is to gather:

  • A list of renovations and approximate completion dates.
  • Available permits and supporting records.
  • Details about materials, finishes, and major equipment.
  • Information about solar equipment and energy improvements.
  • Documentation for additions or converted spaces.

These records help the appraiser understand the property. The contribution of any improvement to appraised value still requires the appraiser’s analysis.


3. Realtors Can Help the Process Move Forward

Listing agents can help by coordinating access and providing accurate property information early.

Buyer’s agents should discuss appraisal timing with the mortgage team before committing to a tight closing schedule. Ask which reporting format will apply and respond promptly if the appraiser or lender needs additional information.

Appraisers and lenders must prepare their systems, workflows, and partners for the transition, according to the official implementation guidance.


4. Homebuyers Should Ask About Timing

The appraisal remains part of the lender’s evaluation of the property supporting the home loan. The redesigned report continues to provide opinions and conclusions for that mortgage purpose.

For buyers, a useful question is: “When do we expect the appraisal back, and how much time is available for lender review?”

The Pennsylvania Association of Realtors cautions that appraisal appointments and report delivery may take longer initially as professionals adjust. That makes early coordination especially helpful when your purchase has a short closing timeline.


5. Homeowners Can Prepare Before Selling or Refinancing

You don’t need to wait until the appraisal is scheduled to organize information about your home.

Create a simple improvement history, gather available records, and make sure the appraiser can access the areas needed for the assignment. If your property has an addition, converted space, or unusual feature, tell your mortgage professional early so questions can be addressed before the closing deadline.

For a refinance, ask your mortgage professional what property valuation is required for your particular home loan.


6. Know the Updated Rollout Dates

The scheduled UAD 3.6 mandate is November 2, 2026, based on the initial submission date of the appraisal report to the Uniform Collateral Data Portal.

A September 30, 2026 announcement provides a temporary policy exception for lenders that request additional transition time from the applicable agencies. Those lenders may continue submitting the older format through May 19, 2027. Beginning May 20, 2027, all new submissions must use UAD 3.6; older-format resubmissions end on June 28, 2027. singlefamily.fanniemae.com

Your mortgage team can confirm which format applies to your transaction.


7. Loan Programs May Have Different Implementation Plans

The new reporting standard supports traditional, hybrid, desktop, and exterior appraisal assignments. It also accommodates FHA, VA, and USDA requirements, but those agencies set their own implementation plans. Confirm the requirements for your specific loan program with your mortgage professional. singlefamily.fanniemae.com


Planning a purchase, preparing a listing, or considering a refinance? Let’s review your home loan options and appraisal requirements early so you know what to expect.


Fresh Home Loan — Independent Mortgage Brokers that Work for the People.


Additional Resources

Other articles:


Why Buying When Rates Are Higher Might Actually Save You Money

https://www.freshhomeloan.com/why-buying-when-rates-are-higher-might-actually-save-you-money

Top 3 Reasons - Why Your Bank Said No... But a Mortgage Broker Might Say Yes

https://www.freshhomeloan.com/top-3-reasons-why-your-bank-said-no-but-a-mortgage-broker-might-say-yes

Why More Luxury Homebuyers Are Choosing a 7/6 Jumbo ARM

https://www.freshhomeloan.com/why-more-luxury-homebuyers-are-choosing-a-7-6-jumbo-arm

Reverse Mortgages in 2026: What Homeowners and Their Families Need to Know

https://www.freshhomeloan.com/reverse-mortgages-in-2026-what-homeowners-and-their-families-need-to-know

Vantage vs FICO: What is the difference?

https://www.freshhomeloan.com/vantage-vs-fico-what-is-the-difference


Garrick Werdmuller

510.282.5456

nmls 242952


For more information give me a call at 510.282.5456 or visit: https://freshhomeloan.com/schedule-a-meeting/ 

All loan approvals are conditional and not guaranteed and subject to lender review of all information. Loan is conditionally approved when lender has issued approval in writing, but until all conditions are met, loan cannot be funded. Specified rates and [products may not be available to all borrowers. Rates subject to change according to market conditions and agreed upon lock times set by borrower. Fresh Home Loan Inc. is an Equal Opportunity Mortgage Broker in California. This licensee is performing acts for which a real estate license is required. Fresh Home Loan, Inc. is licensed by the California Department of Real Estate #02137513 NMLS # 2124104


#AppraisalChanges #UAD36 #HomeAppraisal #RealEstate #RealtorTips #Homebuyers #Homeowners #HomeBuying #Mortgage #Refinance #CaliforniaRealEstate #BayAreaRealEstate #BakersfieldRealEstate #FreshHomeLoan
By Garrick Werdmuller • October 28, 2026
My podcast is back! New Format. Real Estate Business Information and Motivation. Thanks for checking it out and subscribing! 😁 🎧 Our latest episode is the recording of our live UAD 3.6 webinar! Find out what's changing with real estate appraisals and what REALTORS® need to know. 👇 Listen on Spotify: https://open.spotify.com/episode/2qrzPT9wfur9Xs6o4J5mjB #NewPodcastEpisode #SpotifyPodcast #PodcastLife #MotivationAndInformation #RealConversations #RealEstatePodcast #MortgagePodcast #RealEstateMarketing #MortgageBroker #RealtorLife #BusinessMotivation #PersonalGrowth #LiveWebinar #UAD36 #FreshHomeLoan #BayAreaRealEstate #BakersfieldRealEstate
By Garrick Werdmuller • October 14, 2026
Win more listings by showing sellers the value of your local expertise
By Garrick Werdmuller • October 14, 2026
Reconnect, show your appreciation, and stay top of mind this holiday season
By Garrick Werdmuller • October 14, 2026
Friday, October 23, 2026 12:00–12:20 PM Pacific, followed by Q&A Register Here: https://us06web.zoom.us/meeting/register/vA1u-gAETAeKZj_nyHE9Ew In this episode of the GarrickWerdmullerSho , Garrick Werdmuller of Fresh Home Loan explains how real estate agents can use the UAD 3.6 appraisal transition to demonstrate their local expertise and give sellers a compelling reason to choose them. One idea you can put to work immediately: create a résumé for the property. Organize the home’s improvements, renovation dates, available permits, and unique features into a resource that supports your marketing and helps answer questions during the transaction. In this video, you’ll learn: What UAD 3.6 means and how appraisal reporting is changing Why specific improvement details are more useful than “updated throughout” What to include in a property résumé Questions to ask sellers before listing their home How to use AI to organize property information How to explain your preparation during a listing appointment What to ask your lender about the appraisal transition How Fresh Home Loan’s listing marketing tools can support your next listing Your local knowledge matters. Put technology to work helping you show sellers the value of that expertise. Friday, October 23, 2026 12:00–12:20 PM Pacific, followed by Q&A https://us06web.zoom.us/meeting/register/vA1u-gAETAeKZj_nyHE9Ew Connect with Garrick Werdmuller President & CEO | Fresh Home Loan Inc. 📱 Bay Area: (510) 282-5456 📱 Bakersfield: (661) 998-9588 📧 garrick@freshhomeloan.com 🌐 http s ://www.freshhomeloan.com Independent Mortgage Brokers that Work for the People. Presentation reflects information available in October 2026. Confirm current appraisal requirements and timelines with your lender. A property résumé is an optional preparation tool and does not guarantee an appraised value. #GarrickWerdmullerSho #UAD36 #ListingPresentation #RealEstateAgents #PropertyResume #FreshHomeLoan
By Garrick Werdmuller • October 5, 2026
Elevating Your Listing Presentation with UAD 3.6 Win more listings by showing sellers the value of your local expertise. Stay ahead of AI, technology, and industry changes—and turn what’s new into a competitive advantage at your next listing appointment. Instead of simply saying, “I know the neighborhood,” show them how you’ll document their property, explain the competition, and coordinate with the lender early. Join Us Live: Appraisals Are Changing: What You Need to Know About UAD 3.6 Friday, October 9, 2026 12:00–12:20 PM Pacific | Live on Zoom Register for the Webinar https://us06web.zoom.us/meeting/register/cGcRACrDSKifUbss1h88OQ#/registration Garrick Werdmuller | Fresh Home Loan  Independent Mortgage Brokers That Work for the People #UAD36 #ListingPresentation #WinMoreListings #RealtorEducation #LocalExpertise #AIForRealtors #RealEstateTechnology #RealEstateMarketing #FreshHomeLoan
By Garrick Werdmuller • October 1, 2026
Join me for a FREE live Zoom presentation about the new appraisal reporting standard and how to prepare for your next purchase, sale, or refinance.
By Garrick Werdmuller • September 17, 2026
Thinking about buying a home while mortgage rates are high? Learn how less competition, seller credits and negotiating power could save you money.
By Garrick Werdmuller • August 20, 2026
Looking to Consolidate Debt and do some Home Improvement? Got a “COVID Mortgage Rate”? Don’t Touch It!!!
By Garrick Werdmuller • August 11, 2026
Para muchos propietarios de 62 años o más , una hipoteca inversa puede ser mucho más que un préstamo: puede ser una poderosa herramienta de planificación financiera. Después de pasar décadas acumulando capital en una vivienda, muchos jubilados descubren que una parte importante de su patrimonio está concentrada en su propiedad. Una hipoteca inversa puede ayudar a aprovechar parte de ese capital y convertirlo en fondos disponibles, al mismo tiempo que permite a los propietarios continuar viviendo en la casa que aman. Aunque una hipoteca inversa no es adecuada para todos, puede ofrecer beneficios importantes para el prestatario adecuado. A continuación, presentamos cinco razones por las que vale la pena considerar una hipoteca inversa. 1. Generar Ingresos Adicionales Durante la Jubilación La jubilación suele implicar un cambio importante en el estilo de vida. Aunque los años de trabajo hayan quedado atrás, los gastos mensuales no desaparecen. Para muchos jubilados, una hipoteca inversa puede ayudar a cerrar la brecha entre los ingresos de jubilación y los gastos cotidianos. Los fondos recibidos de una hipoteca inversa pueden utilizarse para: Complementar los ingresos de jubilación Cubrir gastos del hogar Crear una red de seguridad financiera Mejorar el flujo de efectivo durante la jubilación Debido a que los fondos de una hipoteca inversa son dinero proveniente de un préstamo y no ingresos obtenidos por trabajo, generalmente no se consideran ingresos sujetos a impuestos. Para los propietarios que cuentan con un capital considerable en su vivienda, pero tienen activos líquidos limitados, una hipoteca inversa puede proporcionar una valiosa flexibilidad financiera. 2. Acceder al Capital de tu Vivienda de la Manera que Mejor se Adapte a Ti Una de las principales ventajas de una hipoteca inversa es la flexibilidad. Dependiendo del programa, los propietarios pueden elegir recibir los fondos como: Una suma global Pagos mensuales Una línea de crédito Una combinación de diferentes opciones de pago Esta flexibilidad permite adaptar el préstamo de acuerdo con los objetivos financieros y las necesidades de jubilación de cada propietario. Ya sea que necesites ingresos mensuales constantes o acceso ocasional a fondos, una hipoteca inversa puede estructurarse para adaptarse a tu situación. 3. Eliminar los Pagos de una Hipoteca Existente Muchos propietarios utilizan una hipoteca inversa para liquidar una hipoteca tradicional existente. Al eliminar un pago hipotecario mensual, los jubilados pueden mejorar significativamente su flujo de efectivo mensual. Para los propietarios que viven con ingresos fijos durante la jubilación, eliminar uno de sus gastos mensuales más importantes puede hacer que administrar el presupuesto sea mucho más sencillo. Aunque los prestatarios deben continuar pagando los impuestos sobre la propiedad, el seguro de vivienda y mantener la propiedad en buenas condiciones, eliminar un pago hipotecario mensual puede proporcionar un alivio financiero considerable. 4. Ayudar a Cubrir Gastos Inesperados La vida está llena de imprevistos, y algunos de los más costosos pueden estar relacionados con gastos médicos, reparaciones del hogar o emergencias familiares. Una hipoteca inversa puede proporcionar acceso a fondos cuando más se necesitan. Muchos propietarios utilizan los fondos de una hipoteca inversa para: Pagar gastos médicos Financiar modificaciones en la vivienda Cubrir costos de cuidados a largo plazo Realizar reparaciones importantes Crear un fondo para emergencias Tener acceso al capital acumulado en la vivienda puede ayudar a los jubilados a evitar depender de tarjetas de crédito con altas tasas de interés, préstamos personales o retirar fondos adicionales de sus cuentas de jubilación durante momentos difíciles. 5. Protección Incorporada Mediante un Préstamo Sin Recurso Una de las protecciones más importantes para los consumidores de las hipotecas inversas asegurad as por la FHA es que son préstamos sin recurso (non-recourse loans). Esto significa que ni el prestatario ni sus herederos deberán pagar más que el valor de la vivienda cuando el préstamo llegue a su vencimiento y sea exigible. Si eventualmente el saldo del préstamo supera el valor de la vivienda, el seguro hipotecario de la FHA cubre la diferencia. Esta protección puede brindar tranquilidad tanto a los propietarios como a sus familias, especialmente durante períodos de incertidumbre en el mercado inmobiliario. ¿Es una Hipoteca Inversa Adecuada para Ti? Una hipoteca inversa no se trata simplemente de pedir dinero prestado: se trata d e crear opciones. Para algunos propietarios, puede ayudar a mejorar el flujo de efectivo durante la jubilación, eliminar pagos hipotecarios mensuales, preservar cuentas de inversión y proporcionar una mayor seguridad financiera. La clave está en comprender cómo funciona el programa y evaluar si se alinea con tus objetivos a largo plazo. La situación de cada propietario es diferente. Por eso, hablar con un especialista experimentado en hipotecas inversas puede ayudarte a determinar si una hipoteca inversa es una buena opción para tu estrategia de jubilación. Reflexiones Finales Para los propietarios que cumplen con los requisitos, una hipoteca inversa puede ser una forma valiosa d e poner el capital acumulado en su vivienda a trabajar, sin tener que venderla ni asumir un pago hipotecario mensual obligatorio. Cuando se utiliza de manera estratégica, puede ayudar a crear flexibilidad, reducir el estrés financiero y proporcionar recursos adicionales durante la jubilación. Las mejores herramientas financieras son aquellas que respaldan tus objetivos y, para muchos jubilados, una hipoteca inversa puede ser una de ellas. Agenda una Consulta Contacta a Fresh Home Loan hoy mismo para analizar tus opciones con un profesional hipotecario con experiencia. https://freshhomeloan.com/schedule-a-meeting/ Garrick Werdmuller President & CEO Fresh Home Loan Inc. 510-282-5456 NMLS 242952 Diana Diaz Operations Manager 510-751-0303 customercare@freshomeloan.com Síguenos en redes sociales: https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@FreshHomeLoan https://www.tiktok.com/@freshhomeloan Todas las aprobaciones de préstamos están sujetas a revisión y aprobación final por parte del prestamista. Los préstamos se consideran aprobados únicamente cuando se emiten por escrito y se cumplen todas las condiciones. Las tasas y productos pueden no estar disponibles para todos los prestatarios y están sujetos a cambios según las condiciones del mercado y los términos de bloqueo de tasa. Fresh Home Loan Inc. es un Mortgage Broker de Igualdad de Oportunidades en California. Esta compañía realiza actos que requieren licencia de bienes raíces. Fresh Home Loan, Inc. está licenciada por el California Department of Real Estate #02137513 | NMLS #2124104. #HipotecaInversa #HECM #PlanificacionParaLaJubilacion #CapitalDeVivienda #PropietariosDeVivienda #IngresosDeJubilacion #AsesorHipotecario #PlanificacionFinanciera #PropiedadDeVivienda #FreshHomeLoan #BienesRaices #LibertadFinanciera 
By Garrick Werdmuller • August 11, 2026
Aunque tanto un HELOC como un HELOAN permiten a los propietarios acceder al capital acumulado en su propiedad sin tener que refinanciar su primera hipoteca existente, están diseñados para diferentes necesidades financieras. ¿Qué es un HELOC? Una Home Equity Line of Credit (HELOC), o línea de crédito sobre el valor acumulado de la vivienda, es una línea de crédito renovable respaldada por el capital de su propiedad. Puede considerarse similar a una tarjeta de crédito, pero generalmente con una tasa de interés mucho más baja porque está respaldada por su vivienda. En lugar de recibir todos los fondos de una sola vez, usted obtiene la aprobación para un límite máximo de crédito y puede retirar dinero según lo necesite durante el período de disposición. Esta flexibilidad hace que un HELOC sea particularmente atractivo para propietarios que tienen gastos continuos o cuyos costos aún no están completamente definidos. Por ejemplo, si está remodelando una cocina, construyendo una ADU (Accessory Dwelling Unit), pagando la matrícula universitaria durante varios semestres o simplemente quiere tener acceso a fondos para futuras oportunidades, un HELOC le permite pedir prestado únicamente lo que necesita y cuando lo necesita. En muchos casos, los propietarios pagan intereses solamente sobre la cantidad que realmente han utilizado, y no sobre el total de la línea de crédito aprobada. Un HELOC también puede funcionar como una red de seguridad financiera. Muchos propietarios establecen un HELOC y mantienen los fondos disponibles para emergencias, oportunidades de inversión o gastos inesperados. Debido a que el dinero está disponible cuando se necesita, ofrece una flexibilidad que un préstamo tradicional de suma global no puede proporcionar. ¿Qué es un HELOAN? Un Home Equity Loan (HELOAN), o préstamo sobre el valor acumulado de la vivienda, es una segunda hipoteca tradicional que proporciona una cantidad fija de dinero en un solo desembolso inicial. A diferencia de un HELOC, donde los fondos pueden utilizarse a lo largo del tiempo, un HELOAN entrega el monto total del préstamo al momento del cierre y se paga mediante mensualidades fijas durante un plazo determinado. Muchos propietarios prefieren un HELOAN cuando saben exactamente cuánto dinero necesitan y quieren la tranquilidad de contar con un pago fijo y predecible. Si está financiando un proyecto importante de mejora de su vivienda con un presupuesto definido, pagando deudas con tasas de interés elevadas, comprando una propiedad de inversión o cubriendo un gasto grande de una sola vez, un HELOAN puede ofrecer certeza y estructura. Debido a que el monto del préstamo, el pago mensual y el calendario de pagos quedan establecidos desde el cierre, muchos prestatarios valoran la simplicidad de saber exactamente cuánto deberán pagar cada mes. No es necesario administrar diferentes retiros de fondos ni preocuparse por saldos fluctuantes. Para los propietarios que prefieren una solución de financiamiento sencilla y estructurada, un HELOAN puede ser una excelente opción. ¿Cuál Opción es Mejor? La respuesta depende de sus objetivos. Si necesita flexibilidad , quiere tener acceso continuo a fondos o espera que sus gastos ocurran a lo largo del tiempo, un HELOC puede ser la opción que mejor se adapte a sus necesidades. Si sabe exactamente cuánto dinero necesita y prefiere un pago fijo con un calendario de liquidación definido , un HELOAN puede ser una opción más conveniente. La buena noticia es que ambos productos pueden permitir a los propietarios acceder al capital acumulado en su vivienda sin modificar su primera hipoteca existente. Para los propietarios que aseguraron tasas hipotecarias históricamente bajas, esto puede representar una ventaja significativa frente a refinanciar el saldo total de su hipoteca a las tasas actuales del mercado. ¿Te gustaría saber qué opción es adecuada para ti? Para programar una cita con Garrick Werdmuller, Presidente y CEO de Fresh Home Loan Inc. , visite: https://freshhomeloan.com/schedule-a-meeting/ Garrick Werdmuller President & CEO Fresh Home Loan Inc. 510-282-5456 NMLS 242952 Diana Diaz Operations Manager 510-751-0303 customercare@freshomeloan.com Redes Sociales https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@FreshHomeLoan https://www.tiktok.com/@freshhomeloan Todas las aprobaciones de préstamos están sujetas a revisión y aprobación final por parte del prestamista. Los préstamos se consideran aprobados únicamente cuando se emiten por escrito y se cumplen todas las condiciones. Las tasas y productos pueden no estar disponibles para todos los prestatarios y están sujetos a cambios según las condiciones del mercado y los términos de bloqueo de tasa. Fresh Home Loan Inc. es un Mortgage Broker de Igualdad de Oportunidades en California. Esta compañía realiza actos que requieren licencia de bienes raíces. Fresh Home Loan, Inc. está licenciada por el California Department of Real Estate #02137513 | NMLS #2124104. #HELOC #HELOAN #PropietariosDeVivienda #ConsejosParaPropietarios #Hipotecas #FinanzasPersonales #FinanciamientoDeVivienda #AgenteInmobiliario #FreshHomeLoan #BienesRaices #ConstruccionDePatrimonio #AsesoriaHipotecaria #LibertadFinanciera